

Carolina Mortgage Insights with Paul Mattos
Sort By Categories
- Charlotte Area Comparisons 16
- Charlotte Neighborhoods 9
- First-Time Homebuyers 46
- Investment Property Loans 21
- Lake Norman 4
- Lake Wylie 4
- Mortgage Process & Education 49
- Mortgage Programs 36
- Mortgage Qualification 50
- Move-Up Buyers 16
- Moving to Charlotte 28
- North Carolina Communities 12
- Refinancing & Home Equity 14
- Regional Guides 7
- Self-Employed & Alternative Income 11
- South Carolina Communities 10
- Veteran Home Buyers 4
Sort By Tags
- Acreage & Land 3
- Appraisals 10
- Bank Statement Loans 9
- Buying Before Selling 13
- Cash-Out Refinance 4
- Charlotte Relocation 52
- Closing Costs 31
- Commission Bonus & Overtime 5
- Condos & Townhomes 14
- Construction Loans 2
- Conventional Loans 19
- Credit & Debt-to-Income 32
- Credit Challenges 6
- Credit Scores 1
- DSCR Loans 11
- Down Payment 37
- Down Payment Assistance 6
- Employment & Income 25
- FHA Loans 15
- Fixed vs. Adjustable Rates 3
- Gift Funds 7
- HELOC 5
- Home Affordability 9
- Home Equity 9
- House Hacking 4
- Jumbo Loans 14
- Luxury Homebuyers 17
- Mortgage Insurance 12
- Mortgage Payments 29
- Mortgage Pre-Approval 71
- Mortgage Rates 14
- Mortgage Underwriting 25
- New Construction 16
- New Job Offer 6
- Non-QM Loans 14
- Property Taxes & Insurance 34
- Rate Buydowns 7
- Real Estate Investors 22
- Refinancing 13
- Rental Income 11
- Self-Employed Borrowers 11
- Seller Credits 12
- Short-Term Rentals 7
- Student Loans 5
- USDA Loans 5
- VA Loans 7
- Waterfront Homes 8
Can VA Buyers Pay Closing Costs?
VA buyers can pay closing costs, and sellers may help cover them. Learn how seller credits, the 4% concessions rule, and the VA funding fee affect cash to close.
VA Loan vs Conventional Loan
Eligible for a VA loan but considering conventional financing? Compare down payment, mortgage insurance, the VA funding fee, seller credits, and total costs.
FHA vs Conventional Loan: Which Is Better?
FHA or conventional? Compare down payment, credit requirements, mortgage insurance, seller credits, and total costs to see which fits your purchase.
Can You Get a Mortgage After Writing Off Too Much Income?
Business deductions lowered the income on your tax returns? Learn how lenders review self-employed earnings and when a bank statement loan may be worth comparing.
What Credit Score Is Needed for a DSCR Loan?
There is no universal DSCR loan credit-score minimum. Learn how lenders weigh credit alongside rental coverage, down payment, reserves, and property details.
Can You Buy an Airbnb Property With a DSCR Loan?
You may be able to finance an Airbnb with a DSCR loan. Learn how lenders assess short-term rental income and what to verify before buying.
How Investors Finance Multiple Rental Properties
Buying another rental takes more than a down payment. Compare conventional, DSCR, equity, and portfolio financing as your property count and reserve needs grow.
Can LLCs Buy Investment Properties?
An LLC can own rental property, but the financing must permit entity ownership. Learn how DSCR loans, guarantees, title, reserves, and documents work.
What Is a DSCR Loan?
A DSCR loan may help an investor qualify using a rental property’s income. Learn how the ratio is calculated and which costs, requirements, and loan terms to review before choosing one.
How Commission Income Is Calculated for Mortgages
Yes, you can qualify for a mortgage with commission income. Learn how lenders average W-2 and 1099 commissions, handle rising or falling pay and what to prepare.
Can Travel Nurses Buy a House?
Travel nurses can buy homes, but contracts, overtime, employment gaps, and tax-free stipends require careful review. Learn how lenders evaluate travel nurse income and which documents to prepare before applying.
Can Nurses Use Overtime Income for a Mortgage?
Nurses can often use overtime, shift differentials, bonuses, and PRN earnings to qualify for a mortgage. Learn how lenders average variable income and what happens when overtime is declining.
Can Truck Drivers Qualify for a Mortgage?
Truck drivers can qualify for mortgages, but W-2 drivers, mileage-paid employees, lease operators, and owner-operators require different income calculations. Learn how lenders review trucking income, deductions, deposits, and truck payments.
How Bank Statement Loans Work
Learn how bank statement loans calculate income for self-employed borrowers, including eligible deposits, expense factors, down payments and reserves.
Mortgage Options for Business Owners
Business owners may qualify with conventional, bank statement, 1099, P&L, asset-depletion or DSCR loans. Learn how lenders calculate income.
Can 1099 Workers Qualify for a Mortgage?
1099 workers can qualify for traditional or alternative-documentation mortgages. Learn how lenders calculate income, expenses, history and affordability.
What Makes a Strong Mortgage Pre-Approval?
A strong mortgage pre-approval verifies income, assets, debts and credit while explaining payment assumptions, conditions and remaining property requirements.
How a Mortgage Broker Saves Buyers Money
A mortgage broker may help buyers save by comparing lenders, loan programs, fees, points and credits. Learn what to compare—and why the lowest advertised rate may not be the lowest-cost strategy.
Why Communication Matters During a Home Purchase
Clear mortgage communication helps buyers understand deadlines, document requests, underwriting, closing costs and what happens next. Learn which updates matter throughout a home purchase.
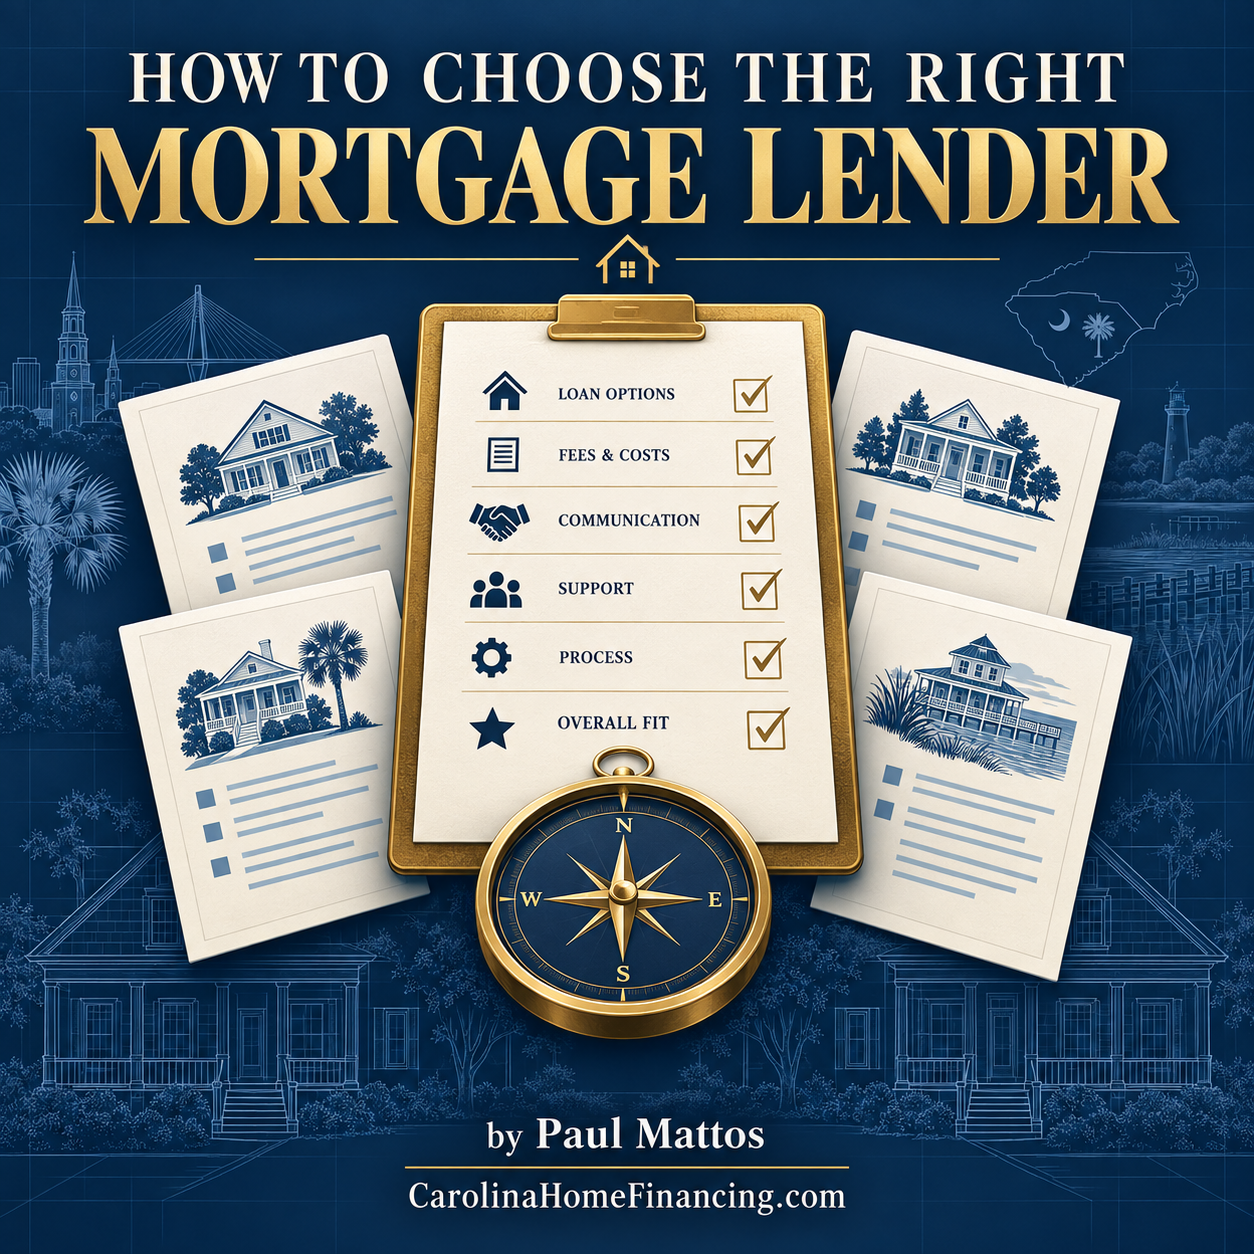
How to Choose the Right Mortgage Lender
Choosing a mortgage lender requires more than comparing advertised rates. Learn how to evaluate Loan Estimates, fees, communication, pre-approval quality, loan programs and closing support.