

Carolina Mortgage Insights with Paul Mattos
Sort By Categories
- Charlotte Area Comparisons 16
- Charlotte Neighborhoods 9
- First-Time Homebuyers 49
- Investment Property Loans 21
- Lake Norman 4
- Lake Wylie 4
- Mortgage Process & Education 54
- Mortgage Programs 35
- Mortgage Qualification 50
- Move-Up Buyers 16
- Moving to Charlotte 28
- North Carolina Communities 12
- Refinancing & Home Equity 15
- Regional Guides 7
- Self-Employed & Alternative Income 11
- South Carolina Communities 10
- Veteran Home Buyers 4
Sort By Tags
- Acreage & Land 3
- Appraisals 12
- Bank Statement Loans 9
- Buying Before Selling 13
- Cash-Out Refinance 4
- Charlotte Relocation 51
- Closing Costs 33
- Commission Bonus & Overtime 5
- Condos & Townhomes 15
- Construction Loans 1
- Conventional Loans 20
- Credit & Debt-to-Income 33
- Credit Challenges 6
- Credit Scores 1
- DSCR Loans 11
- Down Payment 36
- Down Payment Assistance 6
- Employment & Income 25
- FHA Loans 15
- Fixed vs. Adjustable Rates 3
- Gift Funds 10
- HELOC 5
- Home Affordability 12
- Home Equity 10
- House Hacking 4
- Jumbo Loans 14
- Luxury Homebuyers 17
- Mortgage Insurance 15
- Mortgage Payments 31
- Mortgage Pre-Approval 74
- Mortgage Rates 15
- Mortgage Underwriting 27
- New Construction 19
- New Job Offer 6
- Non-QM Loans 14
- Property Taxes & Insurance 37
- Rate Buydowns 7
- Real Estate Investors 22
- Refinancing 14
- Rental Income 11
- Self-Employed Borrowers 11
- Seller Credits 12
- Short-Term Rentals 7
- Student Loans 5
- USDA Loans 5
- VA Loans 7
- Waterfront Homes 8
FHA Will Accept VantageScore 4.0 and FICO 10T Credit Scores in 2027: What It Means for Buyers
Starting January 1, 2027, FHA loans can use VantageScore 4.0 and FICO 10T. Here's how the change works, who it may help and why minimum scores aren't changing.
FHA Appraisal Requirements in North Carolina and South Carolina: What Can Prevent a Home From Qualifying?
Most homes don't need to be perfect to pass an FHA appraisal. Here's what the appraiser looks for, common repair issues in the Carolinas, and what happens next.
Tega Cay, SC Mortgage Guide
Considering a home in Tega Cay, SC? Learn about waterfront and golf-course financing, jumbo and second-home loans, dock rights, property taxes, insurance, HOA costs, and commuting to Charlotte.
What Happens If the Appraisal Comes in Low?
A low appraisal does not automatically end a home purchase. See how it can change financing, what buyers and sellers can negotiate, and when to request a review.
Can I Back Out After Going Under Contract?
Can you leave a home purchase contract? Learn why deadlines, financing, inspections, earnest money, and NC or SC contract terms determine your options.
What Happens If My Loan Is Denied?
A mortgage denial may have a fix, but time matters if you are under contract. Learn what to ask the lender, how to protect deadlines, and what options to review.
Biggest Mistakes First-Time Homebuyers Make
The biggest first-time buyer mistakes happen before the offer: skipping a real budget, forgetting cash beyond the down payment and comparing homes by price alone.
What Bank Statements Do Mortgage Lenders Need?
Buying a home? Learn which bank statements to send, why lenders review deposits and transfers, and how to prepare gift or business funds for mortgage approval.
What Documents Do I Need for a Mortgage?
Start your mortgage pre-approval with the right documents. See the basic checklist and learn when gifts, self-employment, or other income require more records.
Can I Get a Mortgage After Late Payments?
Late payments do not always end your homebuying plans. Learn what lenders may review, how to check your credit report, and what to do before applying.
Can I Buy a House After a Foreclosure?
A foreclosure does not permanently end your homebuying plans. Learn why the completion date matters, how waiting periods differ, and what to prepare.
Can You Get a Mortgage After Writing Off Too Much Income?
Business deductions lowered the income on your tax returns? Learn how lenders review self-employed earnings and when a bank statement loan may be worth comparing.
Mortgage Options for Business Owners
Business owners may qualify with conventional, bank statement, 1099, P&L, asset-depletion or DSCR loans. Learn how lenders calculate income.
What Makes a Strong Mortgage Pre-Approval?
A strong mortgage pre-approval verifies income, assets, debts and credit while explaining payment assumptions, conditions and remaining property requirements.
Why Communication Matters During a Home Purchase
Clear mortgage communication helps buyers understand deadlines, document requests, underwriting, closing costs and what happens next. Learn which updates matter throughout a home purchase.
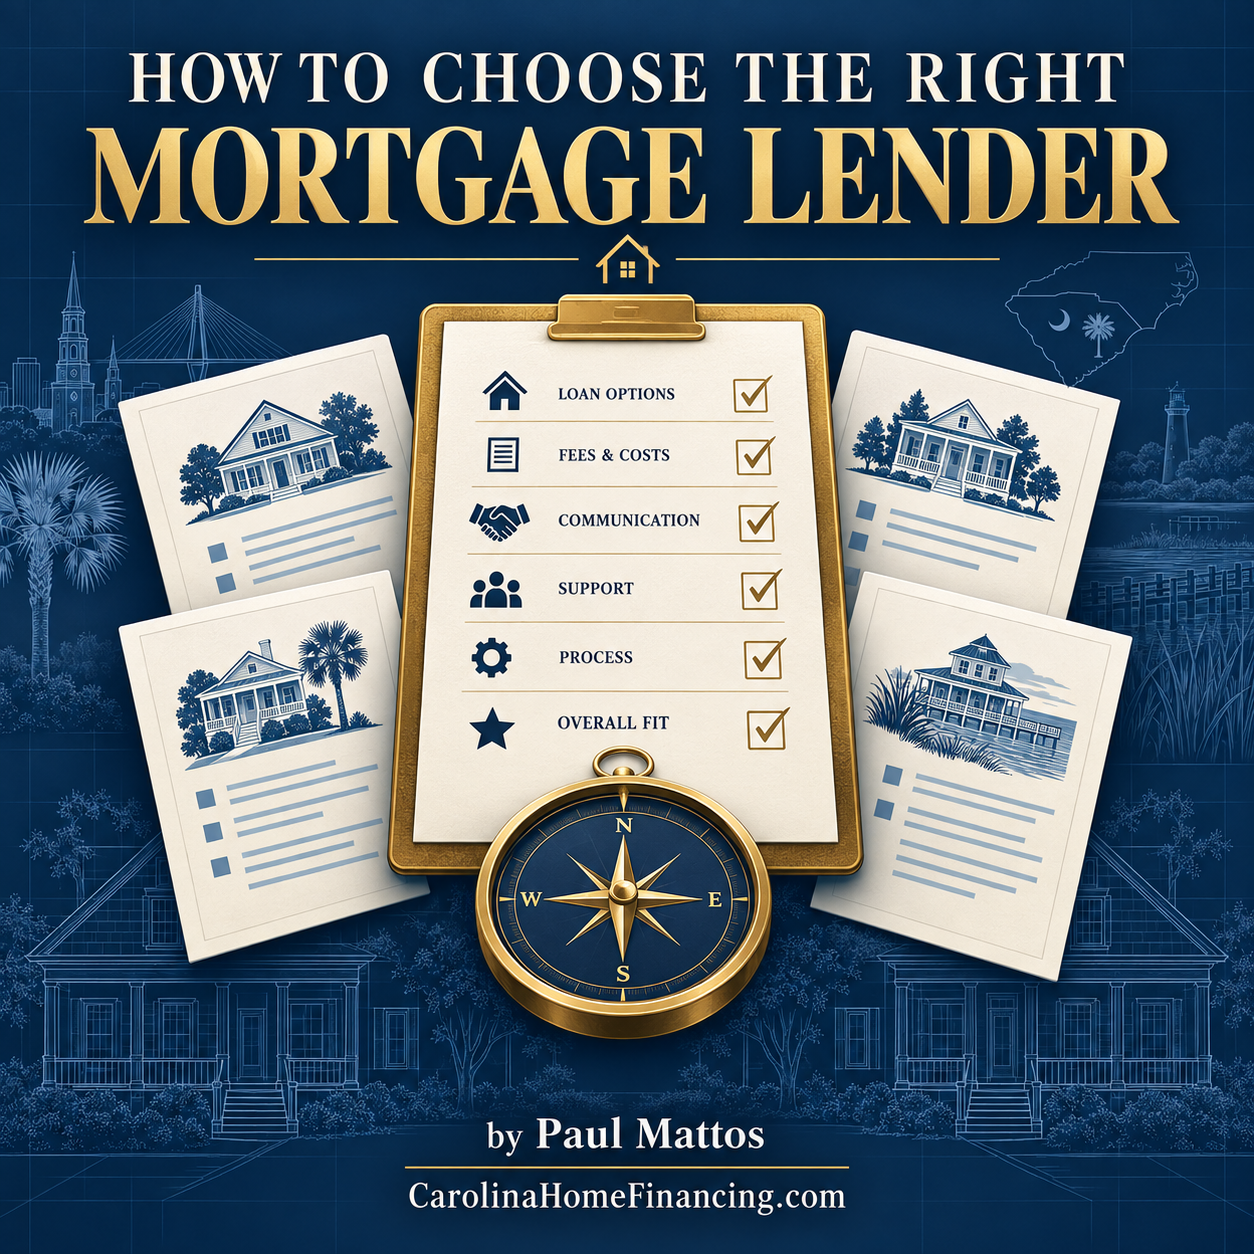
How to Choose the Right Mortgage Lender
Choosing a mortgage lender requires more than comparing advertised rates. Learn how to evaluate Loan Estimates, fees, communication, pre-approval quality, loan programs and closing support.
Questions to Ask a Mortgage Lender Before Applying
Use these 18 questions to compare mortgage lenders before applying. Learn what to ask about pre-approval, rates, fees, Loan Estimates, payments, communication and closing timelines.
What Happens During Mortgage Underwriting?
Underwriting is the lender's final review of your income, assets, credit and the home. Learn what underwriters check, what conditions mean and how to avoid delays.
What Does "Under Contract" Mean When Buying a House?
Under contract means the buyer and seller signed a purchase agreement, but the sale isn't final until closing. Here's what it means in NC and SC and what happens next.
What Not to Do Before Closing on a House
Between contract and closing, lenders keep checking your credit, job and accounts. Here's what not to do before closing, why it matters and what to do instead.